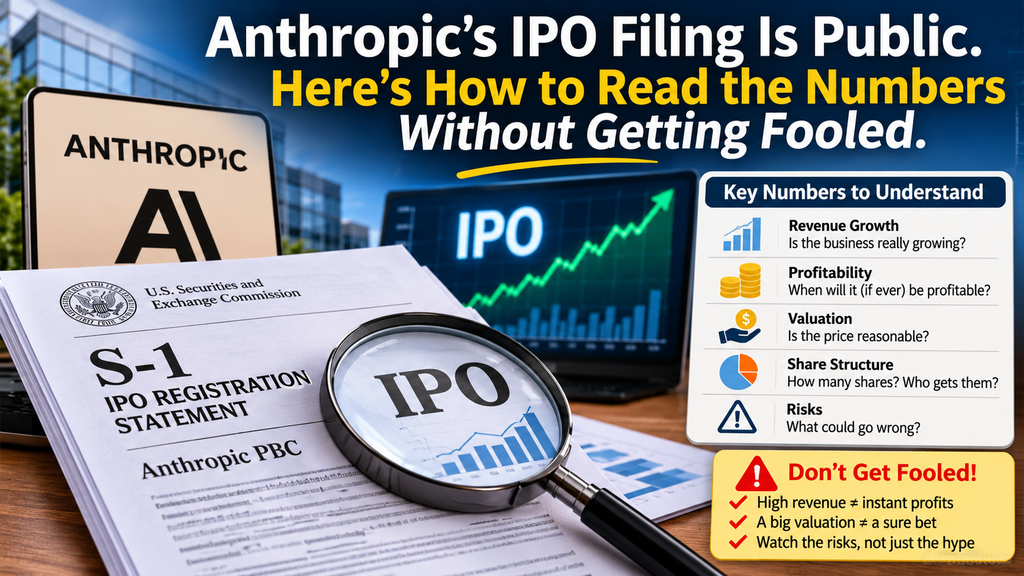
We stated in this newsletter last month that the first public tour of a frontier AI facility will be among the year’s most valuable publications. On Monday, October 26, Anthropic released their S-1 to the public. According to sources, a roadshow will begin the week of November 9 and the company will list on Nasdaq under the ticker ANT in the middle of November. Timing is still subject to market fluctuations.
Before we continue, a little note. This is not a stock tip; rather, it is a newsletter about how to interpret a financial document. The headline figures vary depending on who is summarising them, and there is no investing advice here. Before you quote anything, review the actual filing.
The headline numbers
According to coverage of the filing, revenue for the first half of 2026 was approximately $16.3 billion, operating loss was $693 million, and net loss was approximately $80.7 billion.
According to Reuters and other sources, revenue in 2025 was over $4.6 billion, a twelvefold increase over the previous year. According to reports, the potential raise might reach $100 billion at a valuation as high as $2 trillion, surpassing SpaceX’s June sale, which allegedly raised roughly $85.7 billion.
Read those cold and you’d think the company burned the GDP of a mid-sized country in six months. Read them carefully and the picture changes.
Pro Robot Vacuum and Mop
The Dual Zero-Tangle System combines an anti-tangle side brush with the DuoDivide main brush to minimize hair wrap while effectively lifting long…
Three ways the numbers can mislead you
1. Net loss and operating loss tell different stories. The $80.7 billion net loss looks terrifying. But summaries of the filing say roughly $72 billion of it comes from non-cash accounting adjustments tied to convertible notes. That’s a bookkeeping effect, not money leaving the bank. The $693 million operating loss is a better guide to how the underlying business is doing. Still a loss, but a very different scale. When you read any tech S-1, find the operating line first.
2. Run-rate revenue and recognized revenue aren’t the same thing. You’ve probably seen the figure of about $47 billion in annualized revenue from earlier this year. That’s a run-rate, meaning a recent period multiplied out to a full year. The $16.3 billion is revenue actually recognized across six months. They don’t contradict each other. When a company grows this fast, recent months are far bigger than the early months, so the annualized number runs well ahead of the half-year total. Neither is wrong; they answer different questions. Ask which one a claim is using.
3. A valuation multiple depends on which number you pick. At a $965 billion private valuation and $47 billion of run-rate, the multiple is around 20 times revenue. At a hypothetical $2 trillion it’s more than 40 times. Whether that looks cheap or insane depends on how fast revenue keeps growing, and nobody outside the company knows that yet.
What I’d look for in the full document
If you’re going to spend an evening in the filing, these are the sections that tell you the most:
- Compute commitments. Anthropic spends heavily on infrastructure, working with Google and Amazon and, according to reporting, renting GPU capacity from SpaceX’s Colossus 1 data center. The size and length of those obligations show how locked-in the costs are.
- Customer and cloud concentration. Reports say the filing shows heavy reliance on Amazon and Google. How much revenue flows through those relationships, and on what terms, matters for anyone judging risk.
- Margins on the actual product. Revenue growth is easy to admire. Gross margin on serving customers is where you learn whether growth is profitable at the unit level.
- Risk factors. Boring to read, often the most honest part of any S-1. It’s where companies describe what could go wrong in their own words.
Zoom PodTrak P4next Podcast Recorder with 4 Inputs + AI Noise Reduction
Four XLR inputs with multitrack recording support up to four people plus a call-in guest, giving you flexibility for in-person and remote…
Why this matters even if you’ll never buy a share
Two reasons, and both land on founders.
First, it’s a stress test for the whole AI economy. Investors have become more worried about the industry’s huge spending, and this offering is widely seen as a test of whether public markets will fund it. If it prices well, it makes capital easier for AI companies broadly. If it stumbles, expect harder questions in every AI fundraise, including yours.
Second, it’s a reference point for your own vendor risk. If your product is built on Claude, or on any frontier model, a public company has quarterly pressure private companies don’t. That doesn’t mean prices will rise. It does mean it’s smart to know which parts of your margin depend on someone else’s pricing, and what you’d do if it changed.
The OpenAI wrinkle
OpenAI isn’t listing alongside. Reports say Sam Altman called 2026 a bad moment to go public, and Axios put OpenAI’s annual recurring revenue near $70 billion. Anthropic going first means it gets to set the first public benchmark for what an AI lab’s financials look like. Expect OpenAI’s eventual numbers to be compared directly against whatever this filing shows.
What to do this week
- Read the summary section and the financial statements of the filing, not just headlines about it.
- Write down which number you’re being shown each time you see a figure: run-rate, recognized revenue, operating loss or net loss.
- List the three AI vendors your product depends on most, and note what happens to your margins if each raised prices by 20%.
- Bookmark the filing. In six months you’ll want to compare what the company said against what actually happened.
The era of AI labs raising money on private valuations and press releases is closing. What replaces it is a lot of reading. Better to start now.
Know a founder who’s been asking whether the AI boom is real? Forward this their way. Next week: a plain-English glossary of the S-1 terms that trip people up.
Disclaimer: The information provided in this article is for educational and informational purposes only and should not be considered financial, investment, or trading advice. The views and opinions expressed are solely for general informational purposes and do not constitute a recommendation to buy, sell, or hold any financial instrument or investment. Readers are encouraged to conduct their own research and consult a qualified financial advisor before making any financial decisions. Any investment involves risks, and the author or publisher shall not be held responsible for any financial losses or decisions made based on the information presented in this article.